
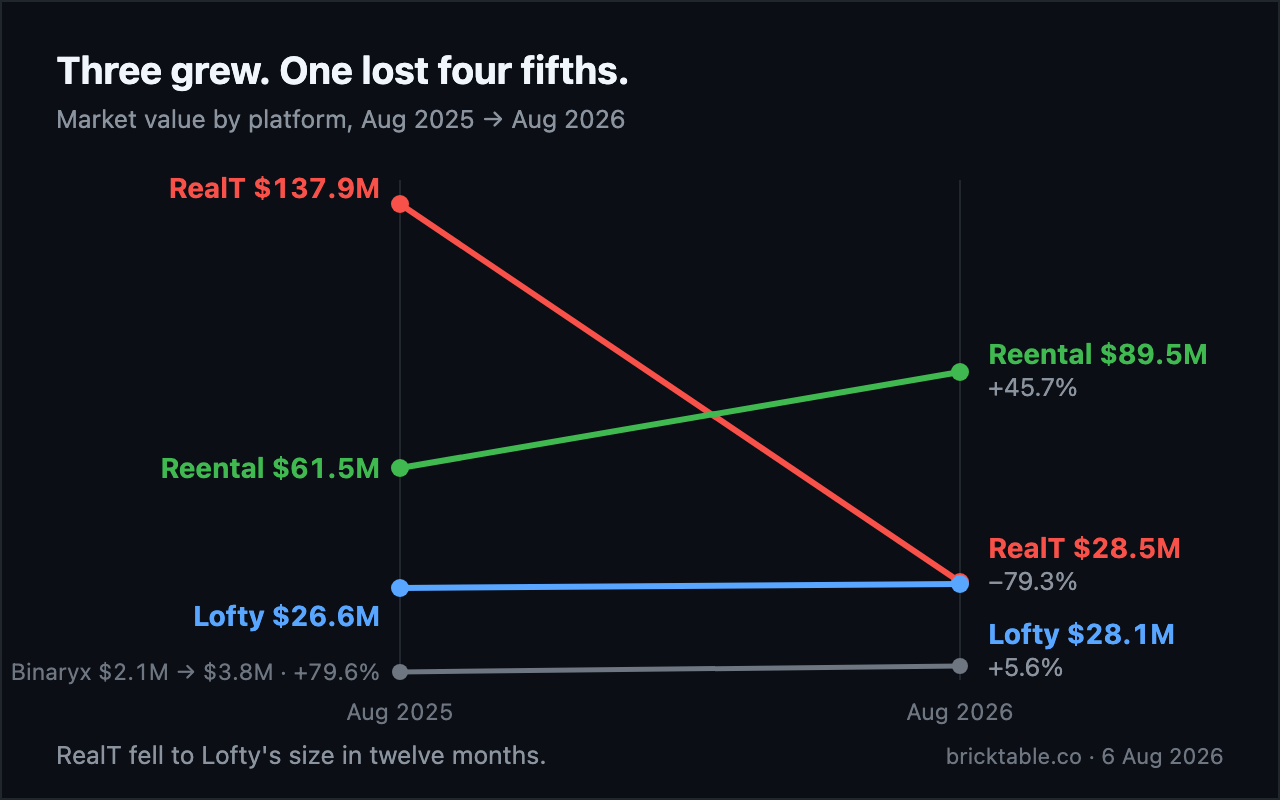
The tokenized real estate market lost a third of its value over the past twelve months. Every dollar of that decline came from a single platform.
We track 1,003 tokenized properties across RealT, Lofty, Reental and Binaryx, and have accrued daily per-platform records since February 2021. Those records show a market that reads as collapsing in aggregate and as growing everywhere except one address.
Findings
- Catalogue market value fell $228.1M → $149.9M (−34.3%) in twelve months.
- RealT alone accounts for −48.0 percentage points of that. Its market value fell −79.3%, from $137.9M to $28.5M.
- Excluding RealT, the market grew 34.6%, from $90.2M to $121.4M.
- Reental grew +45.7% in value and +43.9% in holder positions. Binaryx grew +79.6% in value. Both gained share while a European competitor exited retail entirely.
- Only one of four platforms is still adding inventory. Lofty has not listed a new property in twelve months; RealT in eight.
- 110 of 1,003 listings (11.0%) are currently paying distributions. Excluding RealT, 110 of 249 (44.2%).
- Institutionally-wrapped tokenized real estate does not trade. The largest such asset, at $68.6M, has recorded 328 transfers in its entire history.
- The most-cited industry dataset excludes both RealT and Lofty, and therefore cannot show any of this.
1. The decline is one constituent
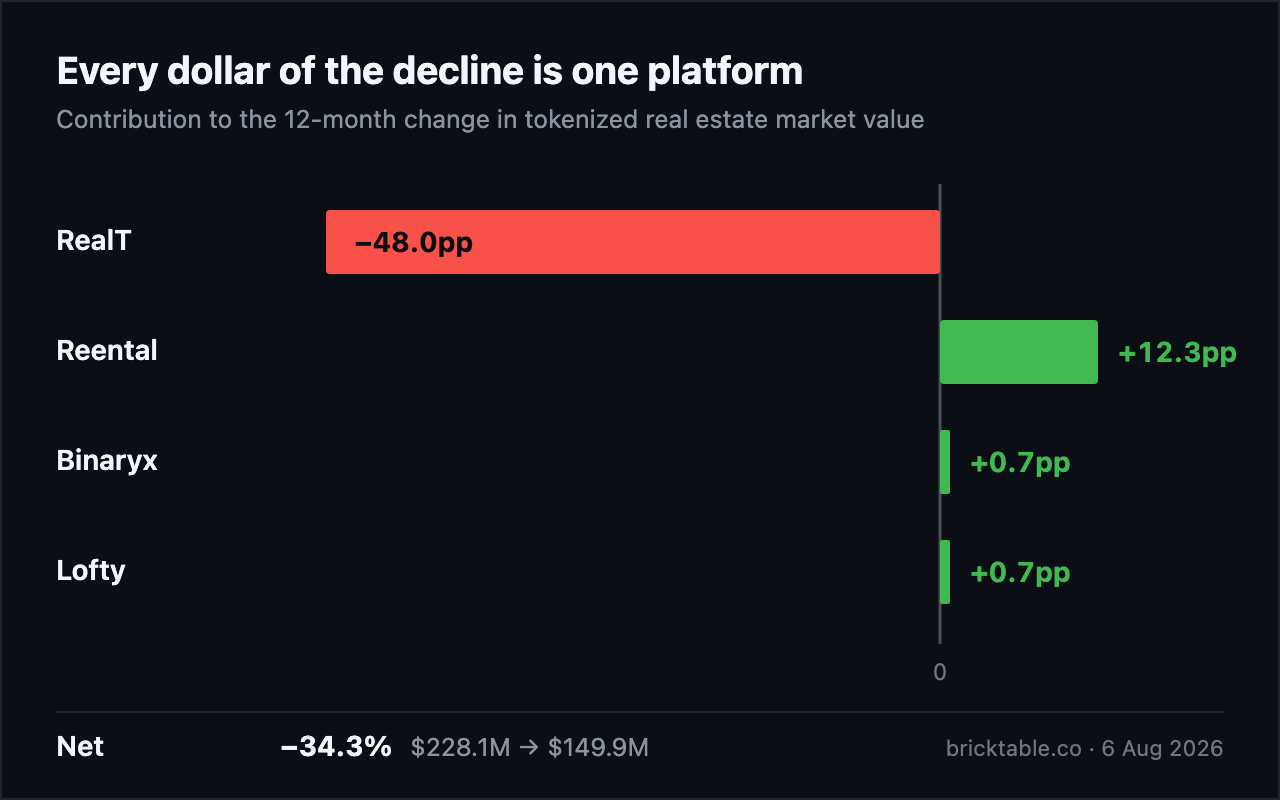
Contribution to the twelve-month change in catalogue market value:
| Platform | Aug 2025 | Aug 2026 | Change | Contribution |
|---|---|---|---|---|
| RealT | $137.9M | $28.5M | −79.3% | −48.0pp |
| Reental | $61.5M | $89.5M | +45.7% | +12.3pp |
| Binaryx | $2.1M | $3.8M | +79.6% | +0.7pp |
| Lofty | $26.6M | $28.1M | +5.6% | +0.7pp |
| Total | $228.1M | $149.9M | −34.3% |
<!-- email-cut -->
Read as one number, the market is in retreat. Decomposed, three of four platforms grew and one lost four fifths of its value.
Holder positions tell the same story from the other side. RealT's grew 1.8% while its value fell 79.3% — the tokens did not leave, the price did.
| Platform | Aug 2025 | Aug 2026 | Change |
|---|---|---|---|
| Reental | 12,504 | 17,998 | +43.9% |
| Binaryx | 6,090 | 7,836 | +28.7% |
| Lofty | 12,163 | 13,170 | +8.3% |
| RealT | 390,302 | 397,502 | +1.8% |
2. What happened at RealT
RealT suspended global rental distributions in February 2026. All 754 of its listings in our catalogue now carry a stalled payout status. None are paying.
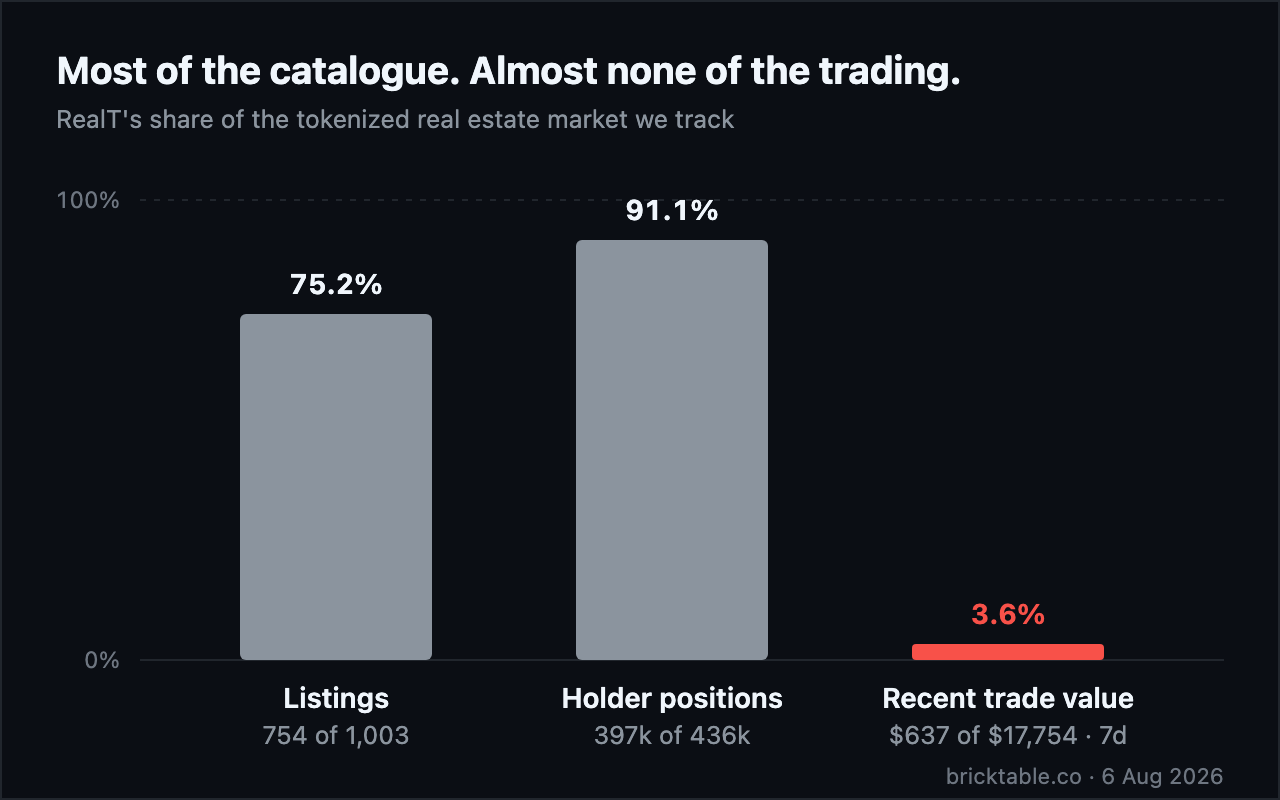
The tokens still trade. 731 of 754 carry live price history and 78 recorded a fill in the last seven days. But the median recent fill on RealT is $5, against $47 on Lofty and $327 on Reental. RealT is 75.2% of our catalogue and 91.1% of all holder positions, and contributed 3.6% of recent trade value.
This is what a tokenized real estate platform looks like after distributions stop: not a delisting, not a wind-down notice — a price that falls four fifths while the holder count holds steady and the tape thins to dust.
We are not aware of another full-catalogue record of this event.
3. Supply has stopped almost everywhere
Last new listing, by platform:
| Platform | Last new listing | Elapsed |
|---|---|---|
| Reental | 5 August 2026 | 1 day |
| Binaryx | 6 May 2026 | 3 months |
| RealT | 5 December 2025 | 8 months |
| Lofty | 25 August 2025 | 12 months |
Lofty's own records confirm it: properties created per year run 18 (2021), 14 (2022), 5 (2023), 28 (2024), 17 (2025), and zero in 2026. Its most recent property was created 12 August 2025.
Lofty's exchange remains the most active venue we track — 89% of its 82 properties traded within the last seven days, and its holder count and value both rose. The trading is healthy; the pipeline is not. Lofty and Binaryx grew on static inventory. Only Reental grew by listing more.
4. Institutional tokenization has produced almost no trading
Tokenized real estate wrapped for accredited and institutional investors is frequently described as the segment's future. Its on-chain record does not support that.
Groma (GromaCoin, 0xdb433b…79a5, Base) is the largest tokenized real estate asset by distributed value on the standard industry registry, at $68.6M against a Boston portfolio. Its ERC-3643 contract has recorded 328 transfers since launch, across 215 holders. The fifty most recent transfers are all 1.0 GRO from a single issuer address to a new wallet — onboarding, not investment.
The mechanism is structural rather than incidental. ERC-3643 and comparable permissioned standards restrict transfers to whitelisted addresses. A liquidity pool cannot be whitelisted, so these tokens cannot reach a DEX, so no market price forms. Valuation stays a quarterly appraisal in a PDF, and distributions run over bank rails rather than the chain.
The pattern repeats across the segment:
| Issuer | Structure | Consequence |
|---|---|---|
| Groma | ERC-3643, permissioned | 328 transfers in total |
| MetaWealth | Accredited/institutional only | NAV fixed at par ($100/$105) |
| RedSwan | ~$135M listed | Zero distributed; discloses no active secondary market |
| PRYPCO Mint | Emirates ID required to invest | Secondary ledger not public |
| Blocksquare | 188 properties in on-chain registry | 13 have more than one holder |
Compliance and price discovery are being traded against each other, and compliance is winning. That is a defensible choice. It also means these instruments cannot be compared, ranked, or screened, because there is nothing moving to compare.
5. Why the standard numbers miss this
The most-cited registry of tokenized real-world assets puts tokenized real estate at $202.78M in distributed value, down 0.10% over thirty days, with 910 monthly active addresses — itself down 23%. Real estate is the smallest RWA category and the only one contracting, against $16.15B in tokenized U.S. Treasury funds.
That registry does not track RealT or Lofty. Its real estate universe is 105 assets; ours is 1,003.
The omission runs one direction. RealT is the segment's largest failure and its largest holder base; excluding it removes both the losses and the evidence. Meanwhile several of the largest entries in that dataset are marked Represented rather than Distributed — announced but never issued. RedSwan's ~$135M appears entirely in that column.
A market measured without its failures reads as smaller and calmer than it is.
Method
All figures measured 6 August 2026 against 6 August 2025, from BrickTable's own accrued daily series. Market value is last-executed price times outstanding supply, per listing, summed per platform; the series total reconciles exactly to the published catalogue figure of $149,925,274.
Prices are taken from executed fills only. Where a platform settles across multiple assets — RealT fills clear in USDC, WXDAI and Aave-wrapped variants — consecutive prices from different settlement assets are not differenced, because doing so produces artefacts of up to 80% that are indistinguishable from real moves.
Payout status is derived from observed monthly distribution history rather than advertised yield. Trading recency uses each listing's most recent recorded fill. Groma figures are read directly from Base. Blocksquare figures are read from the BlocksquarePropertyRegistry contract on Ethereum mainnet.
Coverage is four retail platforms: RealT, Lofty, Reental, Binaryx. It excludes platforms whose instruments carry no observable market price or realized distribution history, for the reason set out in section 4.
BrickTable tracks price, realized yield and exit liquidity across tokenized real estate. bricktable.co